

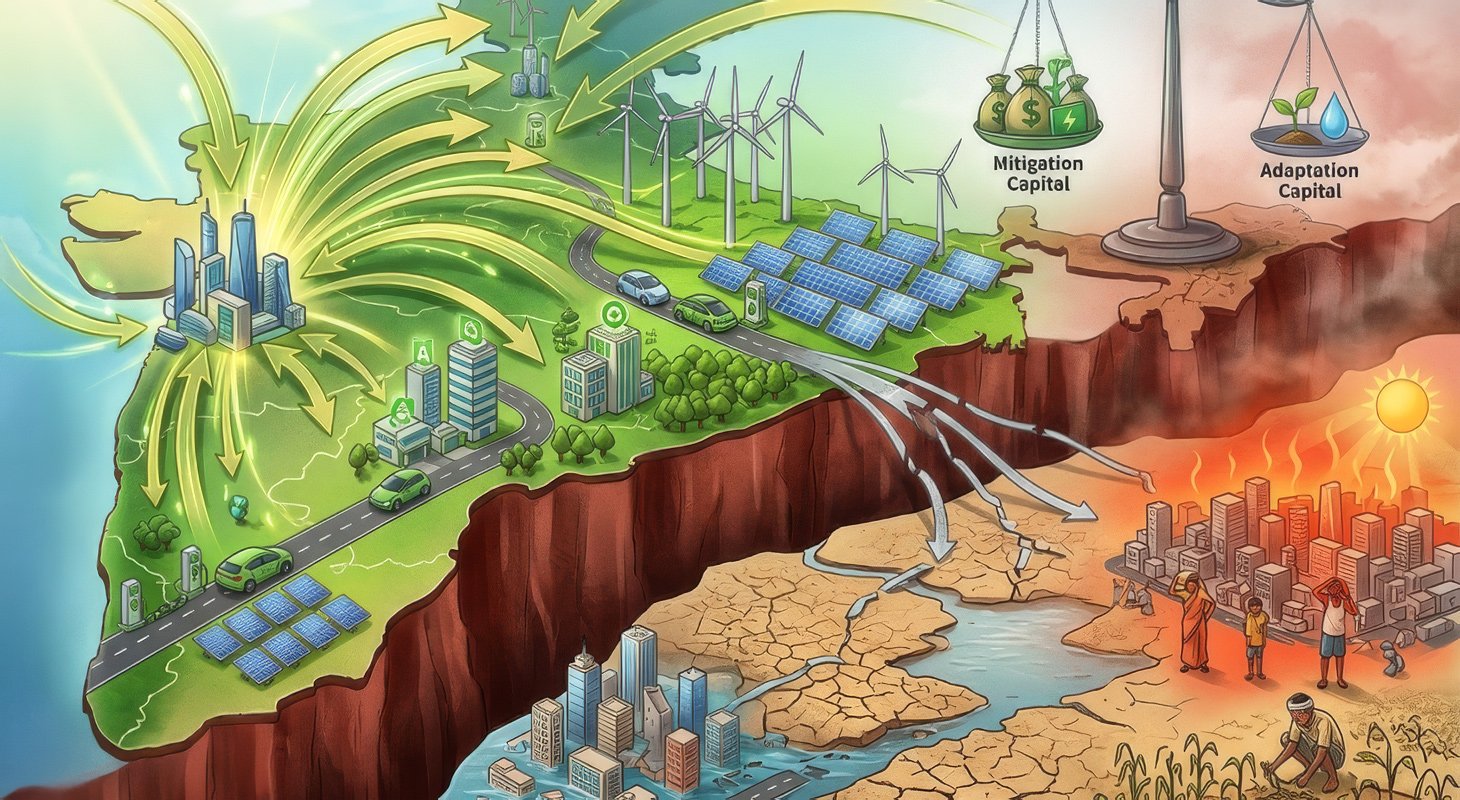
Nearly 70-80% of India's climate capital still flows to mitigation, and we understand why. Renewable energy, EVs, battery storage and climate SaaS offer investors what adaptation largely doesn't yet: scalable, repeatable models with strong demand, clear policy tailwinds and visible exit paths. Investors back business models, not just climate impact, and mitigation has been easier to underwrite and measure in avoided emissions and energy savings.
That imbalance won't hold. As heat stress, water scarcity and urban climate risk intensify across India, we see the real opportunity shifting toward making adaptation investable in its own right, not just fundable through grants and CSR. That means resilience outcomes linked to revenue streams, insurance mechanisms or risk pricing, alongside blended finance and guarantee structures that de-risk early capital. We expect the next phase of Indian climate finance to be defined by whoever cracks that model first, turning adaptation into a real asset class.
Read More